What Is the Difference Between ETFs and Mutual Funds?
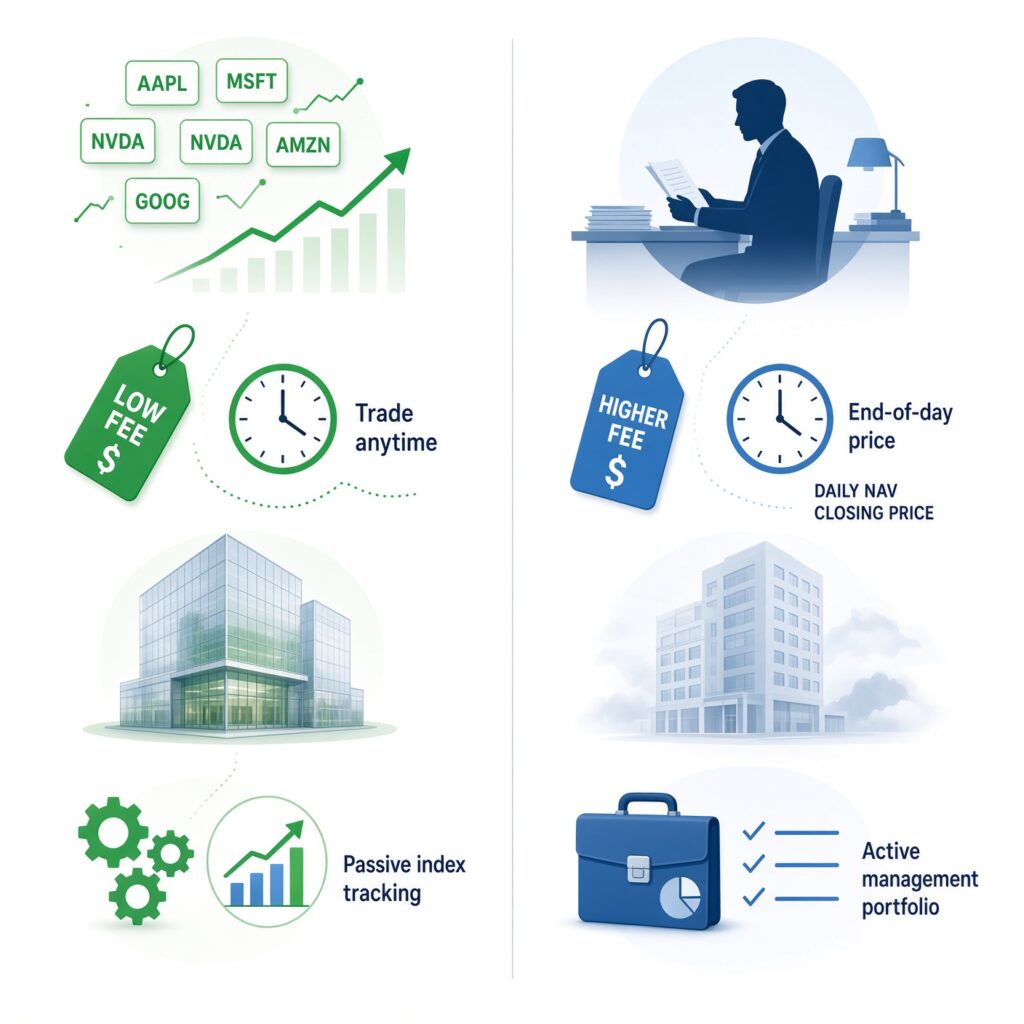
image for illustrative purposes only.
When you begin building an investment portfolio, navigating the vast array of financial products can feel overwhelming. Two of the most popular vehicles for pooling money and investing in a diversified basket of assets are Exchange-Traded Funds (ETFs) and Mutual Funds. At a glance, they look remarkably similar: both allow everyday investors to purchase a slice of hundreds or thousands of securities at once, instantly reducing single-stock risk.
However, beneath the surface lie structural differences that impact how they are traded, how much they cost, and how tax-efficient they can be. Understanding these differences is critical for aligning your investment strategy with your long-term financial goals. Whether you are aiming for retirement wealth accumulation, generating passive income, or balancing risk, choosing between an ETF and a mutual fund can significantly influence your net returns over time.
Defining Exchange-Traded Funds (ETFs) and How They Operate

An Exchange-Traded Fund, commonly known as an ETF, is a collection of securities—such as stocks, bonds, or commodities—that tracks an underlying index, sector, commodity, or other assets. As the name implies, ETFs are listed on public stock exchanges, meaning they trade throughout the regular trading day just like individual stocks.
When you buy shares of an ETF, you are buying a piece of a basket managed by a fund provider. Because they trade on secondary exchanges, their market prices fluctuate continuously in real time based on supply and demand dynamics during market hours.
-
Intraday Liquidity: You can buy or sell ETF shares at any moment the market is open, giving you precise control over your execution price.
-
Passive vs. Active Management: While the vast majority of ETFs are passively managed index funds designed to replicate benchmarks like the S&P 500, an increasing number of actively managed ETFs have entered the market.
-
Brokerage Access: To purchase an ETF, you need a brokerage account. Most modern brokerages offer commission-free trading for standard ETFs, lowering the barrier to entry.
Defining Mutual Funds and Their Traditional Structure
A mutual fund is a professionally managed investment fund that pools money from many different investors to purchase a portfolio of securities. Unlike ETFs, mutual funds do not trade on public exchanges throughout the day. Instead, they are priced and transacted only once per business day, typically after the market closes.
When you place an order to buy or sell a mutual fund through your broker or directly from the fund company, your transaction is executed at the fund’s Net Asset Value (NAV) calculated at the end of that trading day.
-
End-of-Day Pricing: Investors do not know the exact execution price until the NAV is computed after market close, eliminating intraday speculation.
-
Professional Management Focus: Historically, mutual funds have been heavily associated with active management, where portfolio managers attempt to outperform a specific market benchmark through research and strategic trading.
-
Automatic Reinvestment and Contributions: Mutual funds excel at automated recurring investments, allowing you to set up fixed dollar contributions deducted straight from your paycheck or bank account to buy fractional shares easily.
Core Structural Differences: Trading Mechanisms and Liquidity
The most immediate practical distinction between ETFs and mutual funds is how and when you can buy and sell them. This mechanics disparity affects short-term tactical trading as well as long-term portfolio rebalancing.
ETFs provide continuous market access. If market conditions shift dramatically on a Tuesday morning, you can log into your brokerage account and execute a trade within seconds at the prevailing market price. This liquidity makes ETFs favored by investors who value flexibility or utilize limit orders, stop-loss orders, and margin accounts.
Mutual funds operate on a closed-loop system. Because all buy and sell orders are pooled and executed once daily at the calculated NAV, you cannot time your exact entry or exit intraday. For long-term buy-and-hold investors, this distinction rarely matters. However, for those requiring absolute control over execution timing, the restriction can be a drawback. Furthermore, some mutual funds impose early redemption fees or short-term trading fees if you sell your shares within a designated window, discouraging rapid speculative flipping.
Cost Comparison: Expense Ratios, Transaction Fees, and Hidden Expenses
Minimizing investment costs is one of the most reliable ways to enhance your long-term compounding returns. Fees eat directly into your earnings, making cost efficiency a primary evaluation metric for any portfolio.
-
Expense Ratios: Both fund types charge an annual management fee known as the expense ratio, expressed as a percentage of your total investment. Generally, index-based ETFs and index mutual funds feature extremely low expense ratios because they require minimal human intervention. However, actively managed mutual funds often carry significantly higher expense ratios to compensate research teams and portfolio managers.
-
Brokerage Commissions: While online brokerages have largely eliminated commissions for standard stock and ETF trades, purchasing certain mutual funds may still incur transaction fees or load charges.
-
Front-End and Back-End Loads: Mutual funds are frequently categorized by share classes that may include “loads.” A front-end load is a commission paid when you purchase the fund, while a back-end load is paid when you sell. No-load mutual funds exist, but evaluating fee schedules requires careful reading of the fund’s prospectus.
Tax Efficiency: Why ETFs Usually Have the Advantage

Taxes can severely erode investment returns, particularly in taxable brokerage accounts. Understanding how capital gains are distributed highlights a major structural advantage for ETFs over traditional mutual funds.
When portfolio managers inside a traditional mutual fund sell underlying securities to meet investor redemptions or rebalance holdings, those sales can trigger capital gains realizations. By law, mutual funds must distribute these capital gains to their shareholders at the end of the year. Consequently, even if your personal portfolio lost value or you did not sell any shares, you may still owe taxes on capital gains generated by other investors selling out of the fund.
ETFs utilize a unique “in-kind” creation and redemption mechanism involving authorized participants. This structure allows fund providers to pass low-basis securities out of the fund rather than selling them for cash, effectively shielding long-term holders from realizing capital gains. As a result, ETFs generally generate fewer capital gains distributions, making them substantially more tax-efficient for taxable brokerage accounts.
Investment Minimums and Accessibility for Everyday Investors
Getting started with investing requires understanding capital barriers. Historically, mutual funds presented a notable hurdle through minimum investment requirements.
Many traditional mutual funds mandate an initial minimum investment ranging from $1,000 to $3,000, and sometimes significantly higher for institutional share classes. Subsequent contributions also have minimum limits, which can temporarily sideline smaller investors.
ETFs, conversely, have a lower structural barrier regarding initial capital. Because ETFs trade like stocks, your entry cost is determined by the market price of a single share. If an ETF trades at $50 per share, you can enter the fund with just $50. Furthermore, the widespread adoption of fractional share trading by modern brokerages allows investors to purchase fractions of both ETFs and stocks with as little as $1 or $5, virtually eliminating traditional investment minimums across the board.
Active Versus Passive Management Strategies Across Both Products
It is a common misconception that all ETFs are passive index trackers and all mutual funds are actively managed. While that was largely true in the early decades of ETFs, the landscape has evolved dramatically.
-
Passive Indexing: Both product types offer massive suites of low-cost index funds tracking major benchmarks like the S&P 500, Nasdaq 100, Russell 2000, or global aggregate bond indices. For pure index investing, expense ratios between comparable ETFs and index mutual funds are exceptionally close.
-
Active Strategies: Active mutual funds have a long history, relying on human expertise, proprietary research models, and macroeconomic forecasting to beat market returns. However, decades of market data show that the vast majority of active managers fail to consistently outperform broad market indexes over long horizons after accounting for fees. Recently, asset managers have introduced active ETFs, which combine active stock-picking strategies with the intraday trading and tax advantages of the ETF structure.
Dividends, Distributions, and Reinvestment Options
Managing cash flow from your investments is another vital consideration for portfolio design. Both ETFs and mutual funds hold income-generating assets, such as dividend-paying equities or coupon-yielding bonds, which require systematic handling.
When dividends or interest payments are distributed, mutual funds typically offer seamless Dividend Reinvestment Plans (DRIPs) that automatically route cash payouts back into purchasing fractional shares of the exact same fund without human intervention or transaction fees.
ETFs also support DRIPs through most major brokerage platforms. However, because standard ETFs trade whole shares on an exchange, uninvested cash residuals from dividends may sit in your brokerage account as cash until your account accumulates enough capital to buy another whole share, unless your broker specifically supports fractional share automatic reinvestment.
Suitability: Matching Your Investor Profile to the Right Vehicle
Determining whether ETFs or mutual funds better suit your financial journey depends on your account type, trading style, and psychological approach to managing money.
-
When ETFs Are Ideal: If you are managing your investments in a standard taxable brokerage account, prefer the flexibility of trading throughout the day, want to minimize capital gains tax drag, and value ultra-low expense ratios, ETFs are generally the superior choice. They fit exceptionally well into modern self-directed wealth-building frameworks.
-
When Mutual Funds Are Ideal: If you prefer a completely hands-off approach centered on automated recurring payroll deductions, want to avoid watching market fluctuations during trading hours, and are investing primarily inside tax-advantaged accounts like a 401(k) or IRA where capital gains taxes are deferred, traditional mutual funds remain an outstanding, frictionless choice.
Building a Balanced Portfolio: Can You Own Both?

Many successful long-term investors do not limit themselves to just one vehicle; instead, they integrate both ETFs and mutual funds strategically across different accounts.
For instance, an investor might utilize mutual funds inside an employer-sponsored retirement account where automatic paycheck deductions and limited fund menus dictate choices. Simultaneously, the same investor might utilize low-cost index ETFs within a personal taxable brokerage account or Roth IRA to maximize tax efficiency and maintain intraday flexibility.
Ultimately, the underlying assets inside the fund—whether stocks, bonds, real estate investment trusts, or international equities—matter far more to your long-term wealth accumulation than the wrapper holding them. By understanding the operational mechanics, fee structures, tax implications, and accessibility of both ETFs and mutual funds, you can construct a resilient, cost-effective portfolio tailored precisely to your financial future.