What Is an Investment Portfolio?
image for illustrative purposes only.
When you embark on your journey toward financial independence, wealth accumulation, and long-term security, you will inevitably encounter one foundational concept: the investment portfolio. For many beginners stepping into the world of finance, the stock market can feel like a chaotic landscape of fluctuating tickers, overwhelming charts, and complex terminology. However, mastering the mechanics of an investment portfolio transforms that chaos into an organized, strategic engine designed to work for you. At its core, an investment portfolio is not merely a random collection of financial assets; rather, it is a cohesive, centralized pool of investments held by an individual investor, financial institution, or managed fund. These assets can span a wide array of financial instruments, including stocks, bonds, real estate investment trusts, mutual funds, exchange-traded funds, commodities, and even cash equivalents. The primary objective of assembling such a portfolio is to deploy capital efficiently so that it generates returns, preserves purchasing power against inflation, and achieves specific financial milestones over time.
To truly appreciate the power of a well-constructed investment portfolio, one must look beyond the individual components and examine the overarching architecture. Every investor possesses a unique financial DNA shaped by their current life stage, income level, risk tolerance, and ultimate objectives—whether that goal is buying a first home, funding a child’s higher education, or retiring comfortably in luxury. Consequently, no two investment portfolios are identical. Two individuals might both invest in the equity markets, yet their portfolios could look completely different based on their timelines and emotional capacity to withstand market volatility. By understanding the foundational anatomy of a portfolio, you take the first vital step toward transforming casual saving into deliberate, strategic wealth building.
The Core Components: What Can You Include in Your Portfolio?

Building a robust investment portfolio requires a comprehensive understanding of the diverse asset classes available in modern financial markets. Each asset class brings distinct characteristics, risk profiles, and return potentials to the table. By blending these diverse tools, investors can construct a resilient financial structure capable of weathering different economic cycles. Let us examine the primary building blocks that make up a sophisticated portfolio:
- Equities (Stocks): Representing ownership shares in publicly traded corporations, stocks historically offer the highest long-term growth potential. When you purchase a stock, you become a partial owner of that business, entitled to a portion of its profits through dividends and capital appreciation as the company expands.
- Fixed-Income Securities (Bonds): Functioning essentially as loans made by the investor to governments, municipalities, or corporations, bonds provide regular interest payments (coupon payments) and return the principal amount at maturity. They generally offer lower returns than stocks but act as a stabilizing anchor during market downturns.
- Cash and Cash Equivalents: Highly liquid assets such as high-yield savings accounts, money market funds, and short-term Treasury bills. While they offer minimal growth, they provide immediate safety, emergency liquidity, and capital preservation.
- Real Estate: Encompassing physical property, real estate investment trusts (REITs), and mortgage-backed securities, real estate provides a tangible hedge against inflation, reliable rental income streams, and excellent diversification away from traditional equity markets.
- Alternative Investments: A broad category including commodities like gold and oil, cryptocurrencies, private equity, venture capital, and hedge funds, designed to enhance portfolio diversification and capture uncorrelated returns.
Asset Allocation: The Single Most Important Decision
Once you understand the individual assets available, the next critical phase involves asset allocation—the strategic division of your total investment capital among these various asset classes. Financial research consistently demonstrates that asset allocation is the primary determinant of a portfolio’s long-term performance and volatility, far outweighing individual security selection or market timing. Your asset allocation strategy acts as the steering wheel of your financial vehicle, dictating how smoothly you travel toward your goals regardless of external road conditions.
Determining your ideal asset allocation depends heavily on two psychological and mathematical pillars: your time horizon and your risk tolerance. Your time horizon refers to the length of time you intend to keep your money invested before needing to withdraw it. A younger investor saving for retirement thirty years down the road has a long time horizon, which permits an aggressive asset allocation heavily weighted toward equities. Conversely, an investor nearing retirement age has a short time horizon and must shift toward a more conservative allocation emphasizing bonds and cash preservation to protect accumulated wealth from sudden market corrections. Risk tolerance, on the other hand, measures your emotional and financial ability to endure declines in the value of your portfolio without panicking and selling at the absolute worst possible moment. Finding the harmonious balance between these two factors ensures that your portfolio matches both your practical needs and your psychological comfort zone.
Diversification: The Ultimate Risk-Management Strategy
An old adage in finance warns investors never to put all their eggs in one basket. This timeless wisdom forms the philosophical foundation of diversification—the practice of spreading your investments across various industries, geographic regions, asset types, and company sizes to minimize exposure to any single catastrophic event. When you concentrate your wealth in a single stock or sector, your entire financial well-being hinges on the success or failure of that solitary entity. If that company faces regulatory hurdles, management scandals, or structural disruption, your portfolio suffers devastating losses.
Effective diversification operates on the principle of negative or low correlation among assets. For instance, when economic growth slows down, cyclical stocks might struggle, but defensive consumer staple sectors or government bonds may hold their ground or appreciate. By combining assets that react differently to economic stimuli, you smooth out the wild swings of market volatility. Modern portfolio theory takes this concept a step further, mathematically optimizing the mix of assets to achieve the maximum possible expected return for a specific level of risk. Through sensible diversification, you do not necessarily sacrifice returns; rather, you eliminate unnecessary, uncompensated risk, paving the way for a smoother and more sustainable wealth-building journey.
Active Versus Passive Portfolio Management Approaches
As you design and implement your investment portfolio, you must decide how it will be managed day-to-day. This brings us to the fundamental dichotomy in modern finance: active versus passive portfolio management. Each philosophy comes with its own set of principles, fee structures, and operational methodologies, appealing to different types of investors based on their personal philosophies and time commitments.
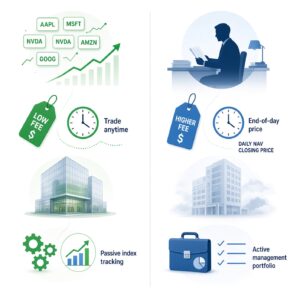
Active management involves hiring professional portfolio managers or dedicating significant personal time to research, analyze, and trade individual securities with the explicit goal of outperforming a specific market benchmark, such as the S&P 500. Active managers attempt to exploit market inefficiencies, capitalize on short-term pricing anomalies, and navigate macroeconomic shifts in real-time. However, this approach typically incurs higher management fees, transaction costs, and potential tax implications due to frequent portfolio turnover. Furthermore, extensive empirical studies show that the vast majority of active managers fail to consistently beat their benchmark indices over long evaluation periods after accounting for all associated fees.
Conversely, passive management embraces the philosophy that financial markets are generally efficient over the long term. Instead of trying to beat the market, passive investors aim to match the market’s overall performance by purchasing low-cost index funds or exchange-traded funds that track broad market benchmarks. This approach emphasizes minimal trading, exceptionally low expense ratios, tax efficiency, and long-term discipline. For the average investor, passive portfolio management has become the preferred standard due to its simplicity, lower friction costs, and historically reliable long-term outcomes.
Periodic Rebalancing: Maintaining Your Portfolio’s Health

Building an investment portfolio and setting an initial asset allocation is only the beginning of the journey. Markets are in a constant state of motion; stock prices rise and fall, interest rates fluctuate, and economic landscapes evolve. Because different asset classes grow at varying rates, time naturally disrupts your original asset allocation plan. For example, if you start with a target allocation of 80% stocks and 20% bonds, a prolonged bull market in equities will cause stocks to grow faster, eventually shifting your portfolio weight to 90% stocks and 10% bonds. Without intervention, your portfolio has quietly become much riskier than you originally intended.
This is where portfolio rebalancing comes into play. Rebalancing is the systematic process of realigning the weightings of your portfolio assets back to your original target allocation. This typically involves selling portions of the asset classes that have outperformed and grown larger, and using those proceeds to purchase units of the asset classes that have lagged or decreased in weight. Crucially, rebalancing enforces a disciplined investing habit: it forces you to automatically sell high and buy low, removing emotional decision-making from your financial life. Investors can rebalance on a calendar schedule—such as reviewing their accounts every six months or once a year—or establish threshold rules, rebalancing whenever an asset class deviates by more than a specific percentage from its target weight.
Common Pitfalls to Avoid When Managing Your Portfolio
Even with a clear understanding of asset allocation and diversification, investors frequently stumble into psychological and tactical traps that sabotage their long-term financial success. Recognizing these common pitfalls allows you to build stronger emotional resilience and safeguard your capital against avoidable mistakes.
One of the most destructive traps is emotional investing, driven by the twin psychological forces of fear and greed. During severe market downturns, fear often triggers panic selling, causing investors to lock in temporary paper losses and miss the subsequent market recovery. Conversely, during euphoric bull markets, greed fuels FOMO (fear of missing out), leading investors to chase overvalued speculative assets just before a correction occurs. Another frequent error is excessive trading and chasing hot tips, which destroys returns through transaction costs and tax inefficiencies. Finally, neglecting to account for inflation and taxes can quietly erode purchasing power over decades, turning what seemed like an impressive nominal return into a disappointing real return. Maintaining a long-term perspective and strictly adhering to your written investment plan provides an effective shield against these behavioral hazards.
Integrating Sustainability and Long-Term Trends
The landscape of investing is continually evolving to reflect broader societal shifts and technological revolutions. Modern portfolio construction increasingly incorporates environmental, social, and governance (ESG) criteria, allowing investors to align their capital deployment with their personal values without sacrificing financial returns. Companies with strong sustainability practices often demonstrate superior risk management, greater operational resilience, and better long-term viability in an increasingly resource-constrained global economy.
Additionally, forward-thinking investors evaluate structural megatrends—such as artificial intelligence, renewable energy transition, biotechnology breakthroughs, and global demographic shifts—when selecting specific sectors or thematic funds for their satellite holdings. While core portfolio holdings should remain broadly diversified across standard index funds, incorporating targeted exposure to secular growth trends can enhance overall performance potential. However, such thematic plays should always represent a minor fraction of your total portfolio, ensuring that core stability remains uncompromised while positioning your wealth to benefit from the future of human innovation.
Building Your Financial Future with Confidence
Mastering the concept of an investment portfolio is an empowering milestone that shifts your relationship with money from passive uncertainty to active, deliberate mastery. By understanding the core asset classes, committing to a well-thought-out asset allocation strategy, embracing broad diversification, and practicing disciplined periodic rebalancing, you establish a resilient foundation for lifelong wealth generation. Remember that successful investing is not a get-rich-quick sprint filled with adrenaline-fueled trades; rather, it is a patient, methodical marathon rewarded by consistency, emotional discipline, and time in the market. As you design or refine your own investment portfolio, keep your long-term goals clearly in sight, tune out the daily noise of financial media, and let structured strategy guide your financial destiny.